An oil ETF is an exchange-traded product that aims to track the price of crude oil, almost always through futures contracts rather than barrels in a tank. For UK investors, most single-commodity oil products are technically exchange-traded commodities (ETCs), because UK fund rules for UCITS ETFs do not allow a fund to track one commodity alone. Returns depend on the change in futures prices, the gain or loss from rolling expiring contracts into later ones, and interest on the cash held as collateral. In April 2020 the expiring May contract for US-traded WTI crude went below zero, according to the US Energy Information Administration.
This explainer covers how the products are built, the difference between Brent crude and WTI crude, contango and backwardation, the UCITS rules, energy shares as an alternative, and the costs and UK tax points to check. For the basics of exchange-traded funds, see what is an ETF.
What an oil ETF holds
Storing physical crude is expensive and impractical for a listed product, so an oil ETF or ETC normally holds futures contracts. A futures contract is an agreement to buy or sell a fixed quantity of oil at a set price on a future date. The EIA explains that such contracts “allow participants to reduce their exposure to swings in prices”, which is why producers, refiners and airlines use them, and that retail investors can gain exposure “using exchange-traded funds (ETFs) with energy derivatives as the underlying assets” (EIA).
The product does not want to take delivery. Before each contract expires it sells it and buys a later one, a process called rolling. The EIA notes that “only about 1% of futures traded go to physical delivery”. The cash the investor paid in is mostly held in short-dated government bills or similar assets as collateral against the futures positions.
- Price exposure comes from the futures contracts.
- The roll adds a gain or a loss, depending on the shape of the futures curve.
- Collateral earns interest, which adds to returns and helps pay the fee.
Futures contracts trade on exchanges in standard sizes and expiry months, and gains and losses on them are settled through margin payments. Because an oil ETF holds futures contracts rather than oil, its value can drift away from the spot price quoted for physical cargoes, especially when the market is under stress.
Brent crude and WTI crude: the two benchmarks
Oil products generally track one of two benchmarks. WTI crude, West Texas Intermediate, is the US benchmark: futures trade on the New York Mercantile Exchange, and holders at expiry “must make or take physical delivery of WTI crude oil in Cushing, Oklahoma”, the EIA says. Brent crude is the international benchmark linked to North Sea oil; in the S&P GSCI commodity index, Brent futures are listed as trading on ICE in the UK (iShares S&P GSCI Commodity-Indexed Trust, annual report).
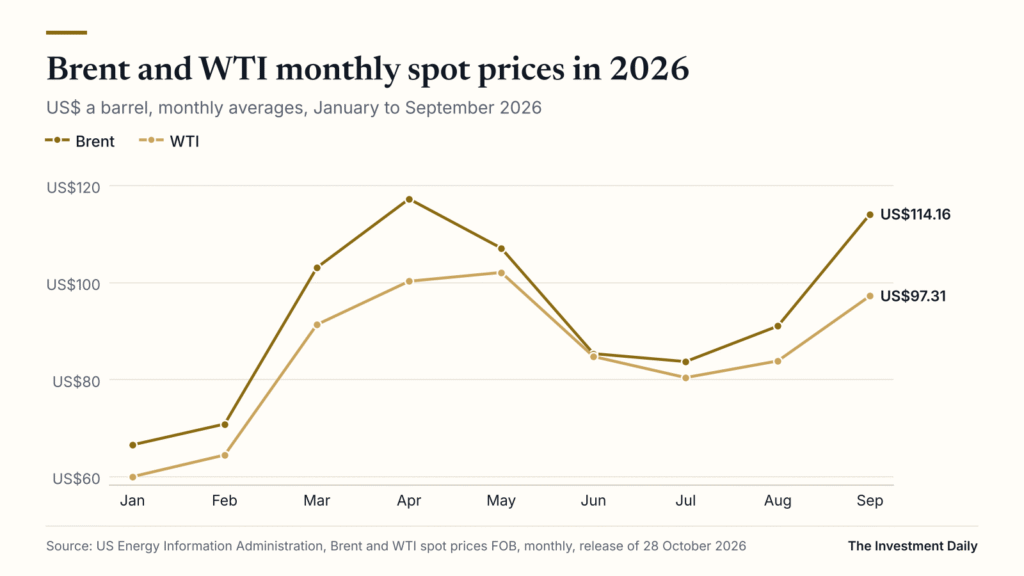
The two usually move together but can diverge sharply. On 21 April 2020, while WTI futures for May delivery were negative, the Brent contract for June 2020 delivery closed at US$19.33 a barrel, the EIA reported. In 2026, with Middle East oil flows disrupted, the gap widened again: the EIA’s daily spot data show Brent at US$123.10 and WTI at US$103.37 on 27 October 2026.
| Annual average spot price, US$ a barrel | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|---|
| Brent crude | 41.96 | 70.86 | 100.93 | 82.49 | 80.52 | 69.14 |
| WTI crude (Cushing) | 39.16 | 68.13 | 94.90 | 77.58 | 76.63 | 65.39 |
| Brent premium over WTI | 2.80 | 2.73 | 6.03 | 4.91 | 3.89 | 3.75 |
Source: EIA, Europe Brent spot price FOB and Cushing WTI spot price FOB, release of 28 October 2026. Past performance is not a guide to future returns.
Prices in 2026 have been far more volatile than in 2025. The EIA’s monthly averages show Brent rising from US$66.60 in January 2026 to US$117.29 in April, falling to US$83.76 in July and climbing to US$114.16 in September; WTI followed a similar path at lower levels.
In its Short-Term Energy Outlook of 6 October 2026, the EIA forecast Brent at an average of US$105 a barrel in the fourth quarter of 2026 and US$84 in 2027, assuming that convoys through the Strait of Hormuz and other workarounds allow Middle East exports to increase (EIA STEO). Forecasts can change sharply: the fourth-quarter figure was US$14 a barrel higher than in the previous month’s outlook.
How oil ETF returns work: futures, roll yield and collateral
The return on an oil ETF is not the same as the change in the spot price you see in the news. It is the sum of the change in the futures price held, the roll yield and the collateral yield, minus fees.
Contango
The annual report of a US commodity index trust gives a clear definition: “contango markets are those in which the prices of contracts are higher in the distant delivery months than in the nearer delivery months due to the costs of long-term storage of a physical commodity prior to delivery or other factors” (iShares S&P GSCI Commodity-Indexed Trust). In contango, the fund sells the cheaper expiring contract and buys a dearer later one, so it ends up with fewer barrels. If prices then stay flat, that shows up as a negative roll yield.
Backwardation
Backwardation is the reverse. The same report describes it as prices that are “higher for contracts with shorter-term expirations than for contracts with longer-term expirations”, which allows the holder to buy “a greater quantity of the later contract”. It notes that the war in Ukraine “contributed to backwardation” in energy futures. Backwardation produces a positive roll yield, but the report warns it “will likely not exist at all times”.
Collateral yield
Because futures need only a margin deposit, most of a fully collateralised fund’s money sits in short-term government securities. The same trust holds US Treasury bills as collateral. Its net investment income, mainly that interest after expenses, came to 3.38% of average net assets in 2025 and 4.39% in 2024; expenses were 0.82% and 0.83%. When interest rates are high, this collateral yield can be a meaningful part of the return of an oil ETF.
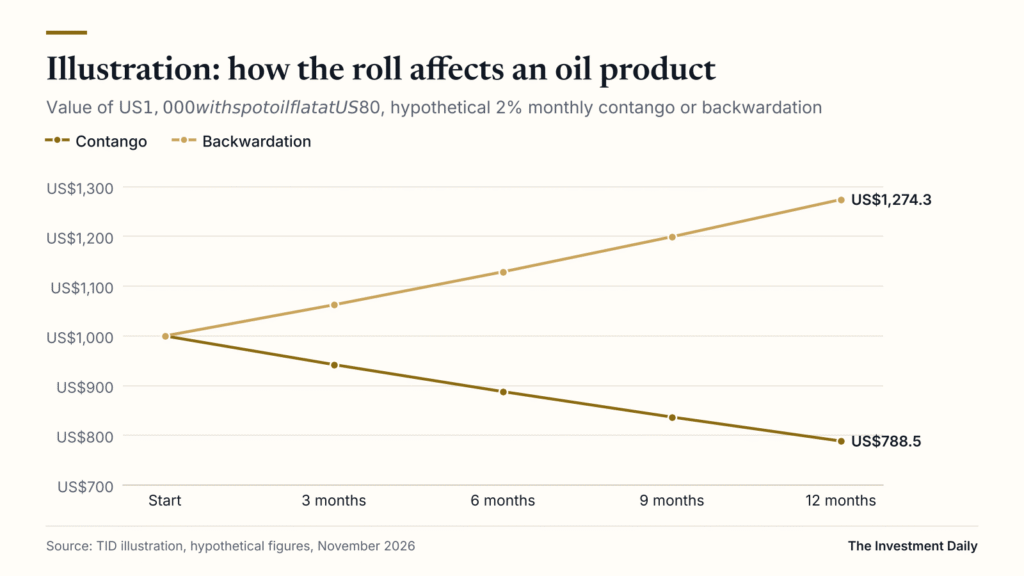
| Illustration only: US$1,000 invested, spot oil flat at US$80 | Start | 3 months | 6 months | 9 months | 12 months |
|---|---|---|---|---|---|
| Contango: each new contract bought 2% above spot | 1,000 | 942 | 888 | 837 | 789 |
| Backwardation: each new contract bought 2% below spot | 1,000 | 1,063 | 1,129 | 1,199 | 1,274 |
The figures are hypothetical and ignore collateral interest and fees. They assume each monthly contract is bought at a 2% premium or discount to a spot price that never moves, and converges to spot by expiry. Real curves change shape all the time, but the arithmetic shows why the futures curve matters as much as the headline price.
April 2020: when WTI futures went below zero
The clearest example of roll risk came on Monday 20 April 2020. The EIA reports that WTI front-month futures on NYMEX “were priced in negative dollars per barrel (b) for the first time since trading began in 1983”, trading as low as minus US$40.32 a barrel at about 2:30pm Eastern time. The EIA’s daily Cushing WTI spot price for that day was minus US$36.98 (EIA).
The cause was storage. Demand had collapsed with Covid-19 travel restrictions, US refinery runs were 24% lower than a year before, and storage at Cushing was 76% full by the EIA’s estimate, with some of the unfilled space possibly already leased or committed. Holders of the May contract who could not take delivery had to sell to anyone willing to take it, “in effect paying a counterparty to allow them to exit their positions”, the EIA said.
The iShares trust’s annual report links the episode directly to the futures curve: crude markets “experienced extraordinarily high levels of contango in the first half of 2020, resulting in a negative price in the May 2020 WTI crude oil futures contract”. It also warns investors that if the futures underlying a product “were to reach a negative price, you could lose your entire investment”. The EIA noted that longer-dated WTI futures contracts and Brent crude stayed positive, so products holding the May contract that week fared far worse than those holding later months.
- Check which contract month an oil ETF holds and when it rolls.
- Check whether the issuer can change the roll rules in a crisis, and how it would tell investors.
- Check what happens to the product if the underlying futures price falls to zero or below.
Why a UK oil ETF is usually an ETC, not a UCITS fund
Many exchange-traded funds sold to UK retail investors are UCITS funds, which must follow strict diversification rules. Under the UCITS Directive as it applies in UK law, a UCITS may invest only in listed categories such as transferable securities, money market instruments, deposits and derivatives on eligible underlyings such as financial indices, and it “shall not” acquire “precious metals or certificates representing them” (UCITS Directive, Article 50). A financial index must be “sufficiently diversified”, built so that “price movements or trading activities regarding one component do not unduly influence the performance of the whole index” (Directive 2007/16/EC, Article 9).
The required diversification is set by reference to the limits for index-tracking funds: up to 20% in a single issuer, which can rise to 35% for one issuer “justified by exceptional market conditions” (UCITS Directive, Article 53). A fund that tracks crude oil alone cannot meet that test. So single-commodity oil exposure cannot be packaged as a UCITS ETF. It is offered instead as an ETC or exchange-traded note: a debt security issued by a company, often a special-purpose vehicle, rather than a share in a regulated fund.
That distinction matters. A UCITS fund is bound by its fund rules and the diversification limits above. An ETC is a promise by the issuer, usually secured on collateral and governed by its prospectus. A broad commodity ETF in UCITS form can include oil, but only within an index that meets the diversification test.
Physical, futures-based and swap-based oil ETF structures
Exchange-traded oil products generally do not hold physical crude, which is costly to store. The choice for an oil ETF is between holding futures directly and using a swap.
| Structure | How it gets exposure | Main extra risks |
|---|---|---|
| Futures-based (direct) | The issuer holds exchange-traded futures and rolls them on a set schedule | Roll yield, margin calls, exchange position limits |
| Swap-based (synthetic) | The issuer enters a swap with a bank that pays the return of a futures index; collateral is held against the swap | Counterparty risk if the bank fails, quality of collateral |
| Leveraged or short | Daily multiple, or inverse, of the futures return, reset each day | Returns over longer periods can differ sharply from the stated multiple |
The iShares trust’s report shows how limits can bite on futures-based products: the US regulator’s position limits cap “the maximum positions that market participants can hold for the spot month” in key contracts. Swap-based ETCs move the exposure to a bank, so check who the swap counterparty is, how collateral is valued and how often it is reset. With any ETC, read the section of the prospectus that explains what happens if the issuer defaults.
Energy shares as an alternative to an oil ETF
Some investors who want exposure to oil buy shares in oil and gas companies, or an equity ETF that tracks an energy sector index, instead of an oil ETF. These are different investments. A producer’s share price depends on the oil price, but also on its costs, reserves, debt, refining margins, dividend policy and management decisions.
- Energy shares and equity ETFs can be UCITS funds, and pay dividends that are taxed as dividends outside a wrapper.
- There is no futures roll, so contango does not directly affect returns.
- Company-specific risks, such as accidents, windfall taxes or write-downs, are added to the oil price risk.
- Over short periods energy shares can move differently from the crude price.
Our dividends and income desk explains how dividend income from shares and funds is taxed. Outside an ISA or pension, dividends above the £500 allowance are taxed at 10.75%, 35.75% or 39.35% in 2026-27 and 2027-28, according to Budget 2026’s OOTLAR Annex A.
Costs, tax and reporting status of an oil ETF
The headline annual fee is only part of the cost. The iShares trust’s sponsor fee, for example, accrues at an annual rate of up to 0.75% of net assets. On top of the fee, you bear the roll yield, the dealing spread on the exchange, any platform charge and the currency effect, because oil is priced in US dollars and a sterling investor gains or loses as the exchange rate moves.
Currency
Oil futures contracts are priced in US dollars. For illustration only, if Brent crude rose 10% in dollar terms over a year while the pound also rose 10% against the dollar, a sterling investor in an unhedged oil ETF would see roughly no gain before costs. Some products offer a currency-hedged version; check whether yours does and what the hedge costs.
Offshore fund status
An ETC may be issued by a company based outside the UK, so the first tax question is whether the security counts as an offshore fund. HMRC says “it is the investor’s responsibility to ensure that they know whether they hold an investment in an offshore fund” (HMRC IFM12152). If it does, reporting status decides the tax on a gain.
HMRC’s helpsheet HS265 says that if you dispose of a reporting fund “you will be subject to Capital Gains Tax on any gain you realise”. On a non-reporting fund, a gain “will normally be treated as an ‘offshore income gain'”, and “you will be subject to Income Tax, rather than Capital Gains Tax” on it, so the capital gains tax annual exempt amount does not cover it.
Check HMRC’s list of approved offshore reporting funds, last updated on 12 October 2026, and the issuer’s own tax documents. If the product is not an offshore fund, gains are normally subject to capital gains tax: Budget 2026 left the annual exempt amount at £3,000 and the rates at 18% and 24% for 2026-27 and 2027-28.
Wrappers
HMRC’s guidance for ISA managers includes securities issued by companies and admitted to trading on a recognised stock exchange among stocks and shares ISA investments. Many London-listed ETCs fall into that category, but each provider decides what it offers. Inside an ISA you do not pay tax on “income or capital gains from investments”, according to GOV.UK, so the offshore fund question does not affect the tax on gains made there.
Oil ETF risks: what to check before you buy
An oil ETF gives exposure to one of the most volatile commodity markets, through futures whose roll can add to or subtract from returns. The EIA’s data show WTI spot below zero in April 2020 and Brent above US$120 in October 2026, a reminder of the range. Past performance is not a guide to future returns.
- Identify the benchmark: Brent crude or WTI crude, and the contract months held.
- Read the roll schedule and look at the current futures curve for contango or backwardation.
- Check the structure: futures-based or swap-based, the collateral and the counterparty.
- Check the total cost: the fee, the spread, platform charges and currency.
- Check the tax position: offshore fund status, reporting status and ISA eligibility.
- Check protection: the FSCS says it can only help where the FCA or PRA “must have authorised the provider or adviser, as well as regulated the service and product it provided” (FSCS), and it never pays for poor performance.
Oil can play different roles in a portfolio, from a short-term trade to a hedge against energy costs, and its weight in any mix is a personal decision. Our guide to building a diversified portfolio explains how single-commodity holdings fit, and the Gold and Commodities desk follows energy markets.