Bed and ISA means selling investments you hold in a general investment account and buying them back inside an ISA, usually on the same day. You cannot transfer existing shares straight into an ISA, so the sale is the price of getting them inside the wrapper. The sale can create capital gains tax above the £3,000 annual exempt amount, at 18% or 24% in 2026 to 2027 (GOV.UK). The 30-day rule that normally matches a sale with a repurchase does not catch a bed and ISA, because ISA holdings are treated as held in a separate capacity (ISA Regulations 1998, regulation 34).
What bed and ISA means
A stocks and shares ISA can only take new money as cash. GOV.UK says shares held outside an ISA cannot be moved in unless they come from an employee share scheme (GOV.UK, ISAs). So an investor with shares or funds in a general investment account who wants them inside the wrapper has to sell, subscribe the cash to the ISA and buy again.
Many platforms run a service that does all three steps in one instruction, often on the same day, so the time out of the market is short. Some offer a similar process for a pension, often called bed and SIPP. The steps are broadly the same everywhere:
- Sell some or all of a holding in the general account.
- Subscribe the cash proceeds to an ISA, within your £20,000 ISA allowance for the tax year (Budget 2026 Annex A).
- Buy the same or a similar investment inside the ISA.
- Keep the contract notes, because the sale is a disposal for tax purposes.
HMRC recognises the process. Its guidance for ISA managers says investments held outside an ISA “can be sold, and the proceeds subscribed to an ISA”, and that buying back the same investments inside the ISA is a “Share Exchange”, sometimes called bed and ISA (HMRC, Manage ISA subscriptions).
The conditions are that the investments are not bought from the investor or the investor’s spouse or civil partner, that they are bought at the open market price, and that any stamp duty or stamp duty reserve tax on the purchase is paid from cash held in the ISA. HMRC also says the sale “is a disposal for capital gains purposes”.
Once the holding is inside the ISA, future dividends, interest and gains on it are free of UK tax. GOV.UK says “You do not pay tax on dividends from shares in an ISA” (GOV.UK). That is the point of the exercise: a small or nil tax cost now in return for sheltering the holding from tax in later years. Our guide to dividend investing after the 2026 dividend tax rise shows what dividend tax costs outside the wrapper.
Capital gains tax on the sale
The sale in the general investment account is a normal disposal. If the price has risen since you bought, you have a gain. You pay capital gains tax only on total gains for the tax year above the annual exempt amount, which GOV.UK calls the tax-free allowance: £3,000 for the 2026 to 2027 tax year (GOV.UK, Capital Gains Tax rates). Annex A to Budget 2026 shows the same £3,000 for 2027 to 2028 (Annex A).
Gains within the basic rate band are taxed at 18%. GOV.UK says that for any amount above the basic income tax band “you’ll pay 24% on gains made from 6 April 2026” (GOV.UK). Your gains are added on top of your taxable income to decide which rate applies, so a basic rate taxpayer with a large gain can pay both rates.
Working out the gain
Shares and fund units of the same class are usually pooled. HMRC’s helpsheet HS284 says that in a Section 104 holding “each share in the holding is treated as if acquired at the same average cost” (HMRC, HS284). If you sell part of a holding, the cost you deduct is that average cost multiplied by the number sold, and dealing costs can usually be deducted as well.
The annual exempt amount has shrunk sharply in recent years, which is why moving holdings into an ISA matters more to investors with gains in a taxable account than it did five years ago.
| Tax year | Annual exempt amount (individuals) | Main rates on gains |
|---|---|---|
| 2021-22 | £12,300 | 10% and 20% |
| 2022-23 | £12,300 | 10% and 20% |
| 2023-24 | £6,000 | 10% and 20% |
| 2024-25 | £3,000 | 10% and 20% to 29 October 2024; 18% and 24% from 30 October 2024 |
| 2025-26 | £3,000 | 18% and 24% |
| 2026-27 | £3,000 | 18% and 24% |
| 2027-28 | £3,000 | 18% and 24% |
Sources: HMRC, Capital Gains Tax rates and allowances, updated 13 April 2026. Rates shown are those for gains on shares and funds; 2027-28 from Budget 2026 Annex A, 28 October 2026.
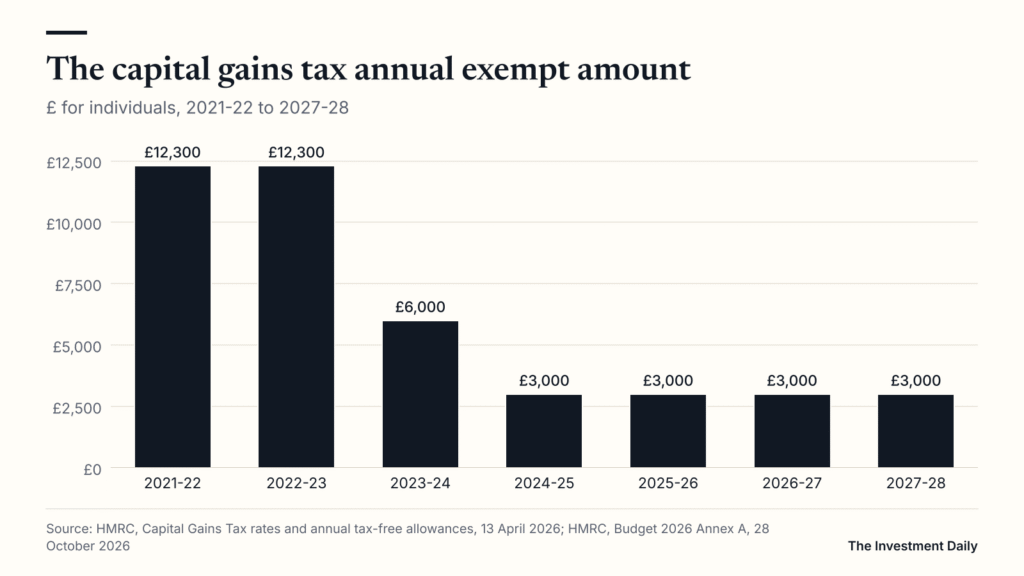
Why the 30-day rule does not stop a bed and ISA
Investors once sold shares one evening and bought them back the next morning to use their allowance, a practice called bed and breakfasting. The share identification rules now stop that, and bed and breakfasting in the old sense no longer works within a single account. HS284 sets the order in which a disposal is matched: first with shares bought on the same day, then with shares bought in the following 30 days, provided the seller was UK resident when they were bought, and only then with the Section 104 holding (HMRC, HS284).
So if you sell shares in a general investment account and buy the same shares back in the same account within 30 days, the sale is matched with the new purchase, not with your old cost. The gain or loss is worked out against the repurchase price. That is the bed and breakfasting rule, in section 106A(5) of the Taxation of Chargeable Gains Act 1992 (HMRC, CG51560).
The separate capacity rule
HMRC’s Capital Gains Manual says the 30-day rule applies only to shares “acquired by the same person in the same capacity” (HMRC, CG51560). It gives the example of a disposal by an individual personally followed by an acquisition as trustee of a trust, which falls outside the rule.
ISA holdings get similar treatment by statute. Regulation 34 of the Individual Savings Account Regulations 1998 says that, for the pooling and identification rules, the holder of ISA investments is treated “as if that person held them in a capacity other than that in which he holds any other securities of the same class” (legislation.gov.uk).
A purchase inside the ISA is therefore not matched with the sale in the general investment account. The sale is matched with your existing holding at its average cost, and the 30-day rule does not apply to the ISA repurchase. The bed and breakfasting rule therefore does not reach the purchase inside the wrapper.
| Sale in a general account, then… | Is the sale matched with the repurchase under the 30-day rule | Result |
|---|---|---|
| Rebuy the same shares in the same general account within 30 days | Yes | Gain or loss measured against the new purchase price |
| Rebuy inside your ISA | No: ISA holdings are a separate capacity | Gain or loss measured against your average cost |
| Your spouse or civil partner rebuys | No: a different person | Gain or loss measured against your average cost |
| Rebuy after 30 days in the same account | No | Gain or loss measured against your average cost, but you are out of the market for 30 days |
Sources: HMRC, HS284; HMRC, CG51560; ISA Regulations 1998, reg 34.
A bed and ISA worked example
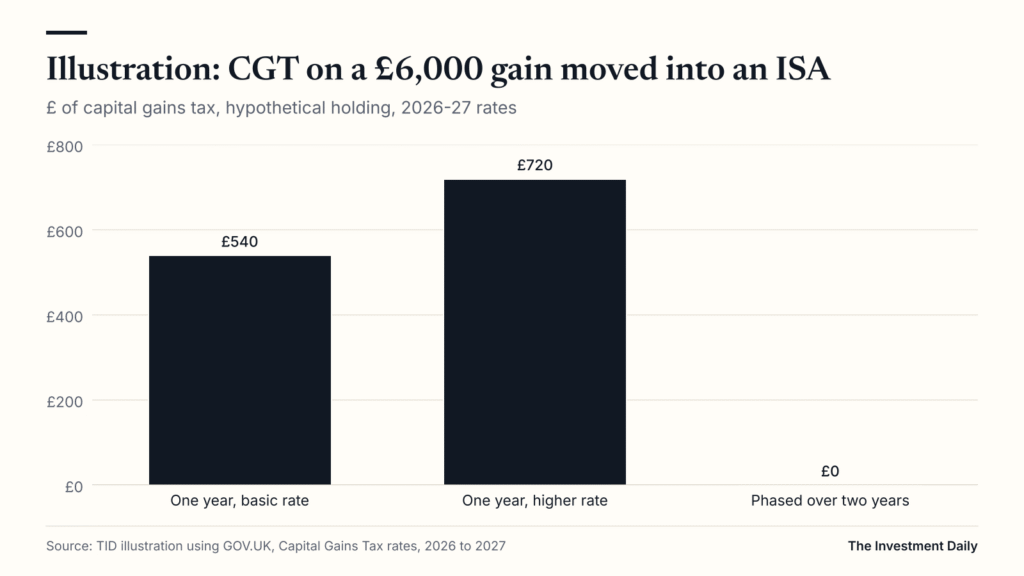
For illustration only. A higher rate taxpayer holds 4,000 units of a global index fund in a general investment account. The Section 104 holding cost £14,000 in total, an average of £3.50 a unit. The units are now worth £5.00 each, or £20,000. The investor has made no other disposals this tax year and has room in this year’s ISA limit.
Option one: everything in a single tax year
Selling all 4,000 units realises £20,000 against a cost of £14,000, a gain of £6,000. After the £3,000 exemption, £3,000 is taxable at 24%, so the tax bill is £720. The £20,000 is subscribed to the ISA, using the whole £20,000 ISA allowance, and the units are bought back inside it, less dealing costs.
Option two: phase it across the tax year end
Selling 2,000 units before 5 April realises £10,000 against a cost of £7,000, a gain of £3,000, which the exemption covers in full. Selling the other 2,000 units on or after 6 April uses the next year’s exempt amount and ISA allowance. If prices are unchanged, the second gain is also £3,000, and the total tax is nil.
The trade-off is market risk: the units left outside the ISA between the two sales can rise or fall. If they rise, the second gain grows. If they fall, the gain shrinks, but so does the investment.
| Illustration | Option one: £20,000 in one year | Option two: £10,000 in each of two years |
|---|---|---|
| Gains realised | £6,000 | £3,000 + £3,000 |
| Exemption used | £3,000 | £3,000 + £3,000 |
| Taxable gain | £3,000 | Nil |
| Tax, higher rate | £720 | Nil |
| Tax, if all within basic rate band | £540 | Nil |
| ISA subscription used | £20,000 in one year | £10,000 in each year |
Rates from GOV.UK: 18% within the basic rate band, 24% above it. Assumes unchanged prices and no other gains or losses.
Costs and time out of the market
A bed and ISA costs money even when no tax is due. The costs to check before dealing are:
- Dealing commission on both the sale and the purchase, unless the platform waives it for this service.
- The spread between buying and selling prices, paid twice.
- Stamp duty of 0.5% on purchases of UK shares (Annex A). Budget 2026 confirmed that a Securities Transfer Tax will replace stamp duty and stamp duty reserve tax on shares from late 2027 (OOTLAR item 1.64).
- Any fees for moving between accounts, and the ISA’s own platform charges.
- Fund dealing: open-ended funds trade at a set valuation point, so the sale and purchase may be priced at different times.
Time out of the market is the other cost. If the sale and repurchase happen at different times, the price can move against you. A same-day service limits that gap, but cannot remove it for funds with daily pricing.
The dealing costs are a deductible cost for the capital gains calculation on the sale. They still reduce what ends up inside the ISA. On a small holding with no gain, the tax saving may be modest compared with the costs, which is why the two figures are usually compared.
Using a spouse or civil partner with bed and ISA
Married couples and civil partners each have their own £20,000 ISA allowance and their own £3,000 annual exempt amount. GOV.UK says “You do not pay Capital Gains Tax on assets you give or sell to your husband, wife or civil partner”, unless you were separated and did not live together at all in that tax year (GOV.UK, Gifts to your spouse).
That allows two common approaches:
- Transfer part of a holding to your spouse first. They take over your cost: GOV.UK says their gain is measured from when you first owned the asset. Each of you can then sell and rebuy in an ISA, using two exempt amounts and two ISA allowances.
- Bed and spouse: you sell, and your spouse buys the same investment with their own money, in their ISA or account. A purchase by a different person is not matched with your sale under the bed and breakfasting rule.
A transfer between spouses is a real gift. The asset belongs to the recipient, and GOV.UK warns that your spouse or civil partner “may have to pay tax on any gain if they later dispose of the asset” (GOV.UK). You also cannot claim a loss on an asset given to a spouse, according to GOV.UK’s losses guidance (GOV.UK).
Bed and ISA with losses, and bed and SIPP
Holdings standing at a loss
A bed and ISA can also be used on a holding that has fallen in value. Because the ISA purchase is not matched under the 30-day rule, the loss on the sale outside the ISA is measured against your average cost. GOV.UK says a reported loss is “deducted from the gains you made in the same tax year”, and unused losses can be carried forward and set against later gains. You can claim up to 4 years after the end of the tax year of the disposal (GOV.UK, Capital Gains Tax losses).
Losses in the same year are set against gains before the annual exempt amount, so a loss can use up part of the exempt amount that would otherwise cover a gain. Losses carried forward from earlier years are used only to bring gains down to the exempt amount.
Bed and SIPP
Bed and SIPP follows a similar pattern with a pension. You sell in the general account, pay the cash into a self-invested personal pension as a contribution, and the scheme buys investments inside it. The pension contribution gets tax relief: GOV.UK says your provider claims relief “at the basic 20% rate and adds it to your pension pot”, and higher and additional rate taxpayers can claim more through Self Assessment (GOV.UK).
The capital gains treatment of the pension purchase is less clear-cut than for an ISA. HMRC has not published guidance on bed and SIPP that we could find, and regulation 34 of the ISA Regulations, which separates ISA holdings for the share identification rules, does not apply to pensions.
As a general explanation only: CG51560 says the 30-day rule matches a disposal only with shares acquired “by the same person in the same capacity”, and gives a disposal by an individual followed by an acquisition as trustee of a trust as an example outside the rule (HMRC, CG51560).
HMRC’s Inheritance Tax Manual describes a SIPP as a personal pension where the member can select “the investments or the assets held by the scheme” (HMRC, IHTM17023). Whether that takes a particular repurchase outside the 30-day rule depends on the facts, and a provider or tax adviser can confirm the position.
The limits are different. Contributions count against the £60,000 annual allowance for 2026 to 2027 and must be within your relevant earnings for relief (GOV.UK). Money in a pension cannot normally be taken before the minimum pension age, which rises from 55 to 57 on 6 April 2028 (HMRC). Our guide to tax-efficient investing compares the ISA and pension routes. The sale in the general account is a disposal for capital gains tax in the same way as for a bed and ISA.
Timing a bed and ISA before 5 April
The ISA allowance and the annual exempt amount both reset on 6 April and cannot be carried forward. That makes the weeks before 5 April the busiest time for these instructions. Two dates matter:
- The trade date of the sale decides which tax year the gain falls in.
- The ISA subscription must be made by 5 April to count against that year’s ISA allowance.
Platforms set their own cut-off dates for bed and ISA instructions before the tax year end, which can fall some days before 5 April, so the platform’s cut-off rather than 5 April itself is the practical deadline. For the 2026 to 2027 tax year the deadline is 5 April 2027, and both allowances reset on 6 April 2027.
One sale in March and another in April, across the tax year end, can use two years of allowances within weeks. The risk is that prices move between the two deals.
Common bed and ISA mistakes
- Rebuying in the general account instead of the ISA. The bed and breakfasting rule then matches the purchase with the sale, and the gain is measured against the new price.
- Withdrawing the proceeds to a bank account and missing the 5 April deadline for the ISA subscription.
- Forgetting gains made earlier in the tax year, including on switches between funds in a general account, which count towards the same £3,000 exemption.
- Going over the £20,000 ISA allowance across all ISAs, including cash ISAs paid into earlier in the year.
- Treating a transfer to a spouse as reversible. The asset belongs to them, and so does any later gain.
- Assuming the investment bought back is identical. A different share class or fund version may have different charges.
Reporting the gain
If you owe tax on a gain, UK residents can report gains on shares through HMRC’s real time Capital Gains Tax service, by 31 December after the end of the tax year, and pay by 31 January, or in a Self Assessment return (GOV.UK, Report and pay your Capital Gains Tax). Keep records of your average cost and every sale.
Before a bed and ISA: a checklist
- Work out your average cost and the gain or loss on the shares you plan to sell.
- Add any other gains and losses in the same tax year, and compare the total with the £3,000 annual exempt amount.
- Check how much ISA allowance you have left, and whether your spouse or civil partner has allowance too.
- Ask the platform about its bed and ISA service, cut-off dates, dealing costs and whether the sale and purchase happen on the same day.
- Check stamp duty and spreads on what you are buying back.
- Consider whether phasing the sale across the tax year end would use two exempt amounts.
- Keep contract notes and report any tax due.
Bed and ISA is a way to move investments from a taxable general investment account into a tax-free ISA, at the cost of a disposal. The 30-day rule does not match the ISA repurchase with the sale, so the gain or loss is worked out against your average cost. With the annual exempt amount at £3,000 and the ISA allowance at £20,000 for 2026 to 2027 and 2027 to 2028, a bed and ISA used each year, and by a spouse as well, can move a holding into the wrapper over time. The value of investments can still fall, and the wrapper does not change that.